
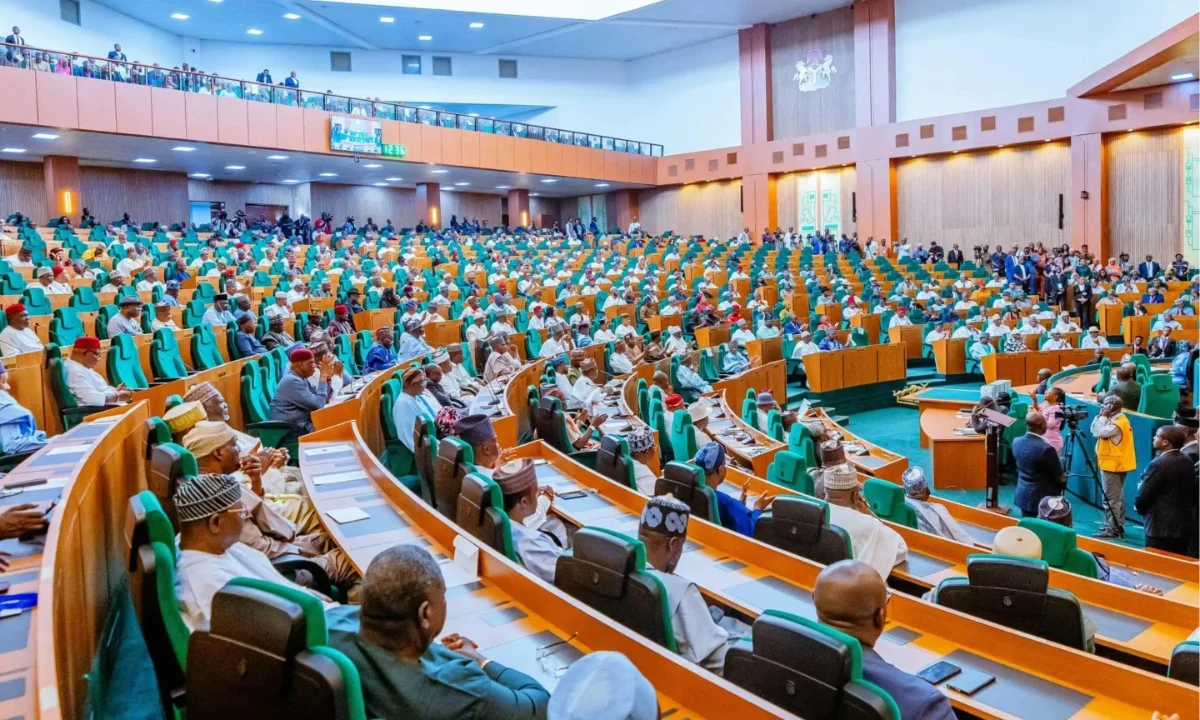
The House of Representatives has intervened in a dispute between the Nigeria Revenue Service (NRS) and the Tertiary Education Trust Fund (TETFund) over N123.48bn allegedly deducted as cost of collection from Education Tax revenues between 2012 and 2024.
The House Public Accounts Committee, chaired by Hon. Bamidele Salam, has resolved to seek the legal opinion of the Attorney-General of the Federation (AGF) to determine whether the four per cent deduction imposed by the NRS on Education Tax collected from oil companies was lawful.
The dispute followed an audit query by the Auditor-General for the Federation, which identified discrepancies between the amount of Education Tax collected by the revenue agency and the funds subsequently remitted to TETFund.
At the committee’s hearing on Wednesday, representatives of both agencies offered conflicting interpretations of the legal provisions governing the deduction.
TETFund argued that the four per cent cost-of-collection provision applied only to non-oil revenue and should not have been extended to Education Tax collected from oil companies.
The Fund’s Director of Finance and Accounts, Dr Gloria Olotu, told the committee that a review conducted following the Auditor-General’s query showed that the NRS had applied the four per cent charge to the entire Education Tax collection without separating the oil revenue component.
According to Olotu, figures provided by the NRS showed that the alleged excess deductions between 2012 and 2024 amounted to N123,486,953,796.24.
She said TETFund had written several letters to the revenue agency seeking a refund and resolution of the matter but had yet to receive a favourable response.
However, an Executive Director representing the NRS, Shettima Tamadi, rejected the refund demand, insisting that the deductions were supported by the law, particularly Sections 15A and 69 of the NRS Act.
Tamadi argued that Section 69 defines non-oil revenue as revenue other than proceeds derived from Petroleum Profits Tax.
He therefore maintained that Education Tax paid by oil companies was still subject to the four per cent cost-of-collection charge because the tax was separate from Petroleum Profits Tax.
According to him, oil companies pay Petroleum Profits Tax separately, and the NRS does not deduct collection costs from such payments.
The committee, however, said the conflicting positions required an authoritative legal interpretation to establish the correct application of the relevant provisions.
Members subsequently resolved to obtain the AGF’s opinion on whether the deductions were lawfully made.
TETFund told the lawmakers that it had previously sought legal advice from the Attorney-General on the matter and agreed to forward the response to the committee.
The committee also resolved to independently request the AGF’s legal opinion before reaching a final decision.
The hearing was adjourned pending the submission of written explanations requested from TETFund and the relevant legal advice.
The outcome of the legal review could determine whether the NRS will be required to refund N123.48bn to TETFund or whether the disputed deductions were made lawfully under the existing statutory framework.